

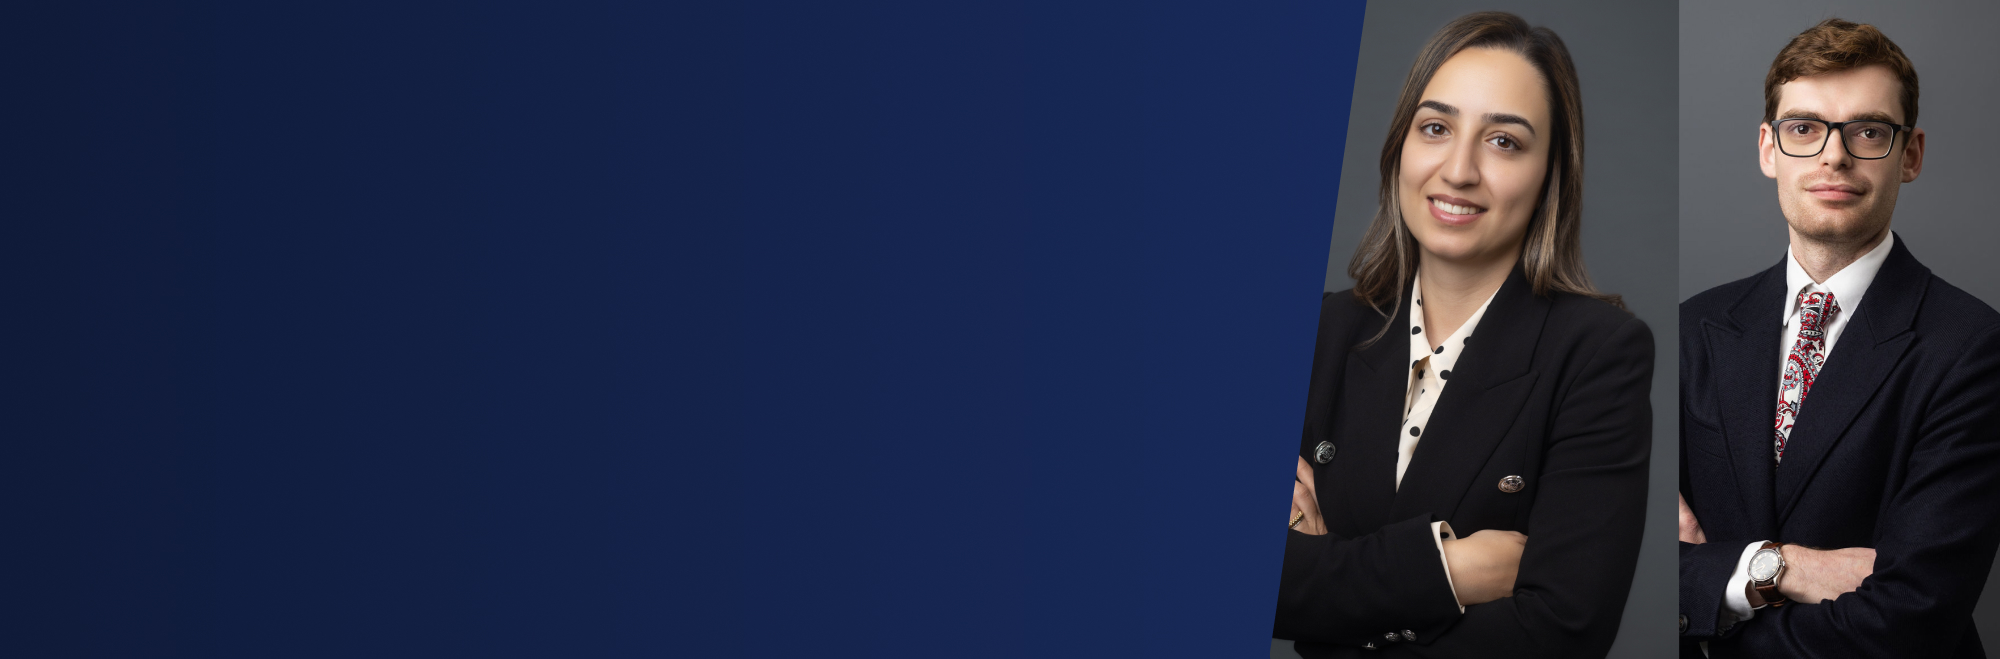


A total and permanent disability (TPD) claim is often made at the hardest point in a person's life: they have stopped work because of illness or injury, their income has gone, and they are facing an insurance process built on forms, definitions and medical evidence. In that situation, who is in your corner matters. Our Parramatta Partner Maria Shwan and Senior Paralegal Jasper Hobba recently received the following five-star Google review from a client they guided through a TPD claim.
"I would like to express my sincere gratitude to Maria for taking on my case and guiding me through this overwhelming process. I truly appreciated her professionalism, dedication and support.
Jasper was also absolutely wonderful throughout the entire process. He helped me with all the paperwork, explained everything clearly, answered my questions and kept me informed every step of the way.
I am extremely grateful to both of them for their hard work, patience, compassion and commitment to my case. Their support made a difficult journey that much easier, and I cannot thank them enough for everything they have done for me.
I would highly recommend their services to anyone needing assistance with a TPD claim. Thank you both from the bottom of my heart!"
Walker Law Group client, TPD claim
What is a TPD claim?
TPD insurance pays a lump sum if you become totally and permanently disabled through illness or injury and are unlikely ever to return to work. Most Australians hold this cover automatically inside their superannuation, often without realising it, and the benefit is paid on top of the super balance itself.
Unlike a workers compensation or motor accident claim, a TPD claim does not require the injury to have happened at work and does not require anyone to be at fault. What matters is whether you meet the definition of total and permanent disability in your policy. The most common definition in super fund policies is "any occupation": you are unlikely ever to work again in any occupation you are reasonably suited to by your education, training or experience. Psychological conditions, spinal injuries, cardiovascular disease, cancer and neurological conditions are among the most common grounds for a successful claim.
Why the paperwork is where TPD claims are won or lost
Our client's review singles out the paperwork, and for good reason. A TPD claim typically involves a member statement, an employer statement and reports from treating doctors, lodged with the super fund and assessed by its insurer. The medical evidence has to do more than describe a condition: it must explain why the person is unlikely ever to return to work they are suited to, in the terms the policy uses. Claims that are well prepared from the outset are commonly resolved in around three to six months once lodged; claims that are poorly documented, or that are declined and have to be challenged, can take twelve months or more.
That is the work Maria and Jasper do every day. Maria was admitted in 2013 and practises in TPD and superannuation insurance claims, leading our disability claims team from the Parramatta office. Jasper works alongside her on disability claims, preparing the evidence, managing the forms and keeping clients informed at each stage. Because superannuation insurance is governed by national law, the team acts for clients across NSW and Australia-wide, including people in regional and remote areas, with a process that can be run largely online.
Clear communication through an overwhelming process
Three things come through in this review: the claim was taken on and run to a result, everything was explained clearly, and the client was kept informed every step of the way. Insurers can request further evidence, independent medical examinations and financial records during an assessment, and the fund's trustee must then review the insurer's decision before any benefit is paid. Each of those steps is an opportunity for a claim to stall or for a claimant to feel lost. Having a lawyer and paralegal who answer the phone, explain what is happening and keep the claim moving makes the difference between a stressful year and a manageable one.
Thank you
We are grateful to every client who takes the time to leave a review. Reviews like this one tell us we are getting the important things right, and they help other people facing a disability claim to find the right support. We have not published our client's name, in keeping with the sensitive and personal nature of TPD claims.
Frequently asked questions
Do I need to have been injured at work to make a TPD claim?
No. TPD cover responds to illness or injury from any cause, provided you meet your policy's definition of total and permanent disability. You can also receive a TPD benefit alongside NSW workers compensation payments; they are separate entitlements.
Is there a time limit for lodging a TPD claim?
There is no fixed statutory time limit for lodging a claim with your fund, and successful claims are regularly made years after a person stopped work. Delay does carry risks, because your cover is assessed at the date you became disabled and evidence becomes harder to reconstruct, so it is best to get advice early.
What does it cost to make a TPD claim with Walker Law Group?
We act for TPD clients on a no win, no fee basis. An initial assessment costs nothing and will tell you what cover you hold, including cover in old or forgotten super funds, and what it is likely to be worth.
Can a declined TPD claim be challenged?
Yes. Declined claims are frequently overturned through the insurer and trustee's internal review process, a complaint to the Australian Financial Complaints Authority (AFCA), or court proceedings as a last resort.
Talk to our TPD lawyers
If illness or injury has left you unable to work and you would like your superannuation cover assessed, our TPD lawyers can help. Call 02 8046 9700 or contact our Parramatta, Manly, Bondi Junction or Newcastle office. For a step-by-step explanation of the process, read our guide to how TPD claims work.


